How can banks apply AI to payments modernization?
Key takeaways:
- AI helps banks modernize payments faster. Multi-agent models cut manual work and boost output without raising costs.
- Most banks plan to use AI for SEPA and ISO 20022. It improves speed, accuracy, and reduces risk of brain drain.
- Success depends on smart AI adoption. With training, strong data, and human oversight, banks can unlock real value.
The rate of change in payments has never been this fast and will never be this slow again. Banks and payment providers around the world are racing to keep up.
No more so than in Europe, where every payment service provider must be able to send and receive instant payments by the end of 2025.
It’s a massive challenge. Banks are spending millions to meet the deadlines. Up to two-thirds of their time and budget is spent on project analysis, testing and business analysis – areas where high-value, payment-specific applied AI can help.
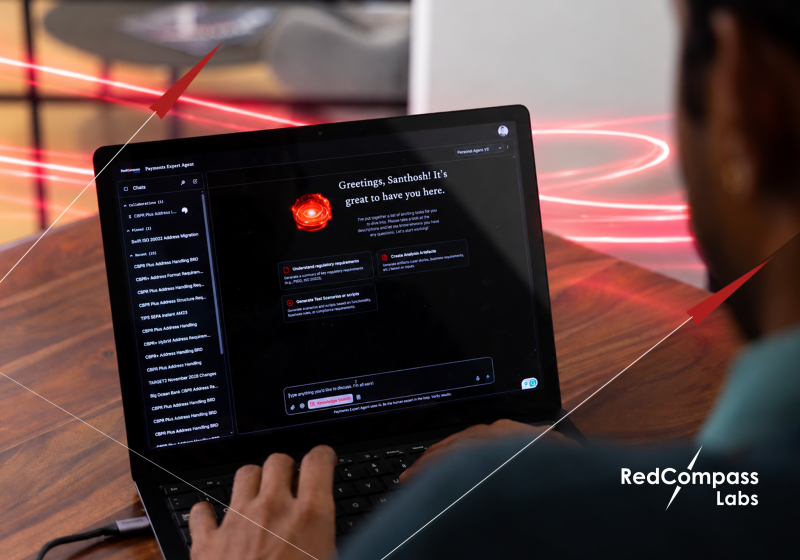
Instead of relying solely on costly, time-consuming manual work, often from third-party consultancies, banks can employ multi-agent AI models to work 24/7 to research, prepare drafts and coordinate workflow while the analysts later review, edit and confirm documentation. And yes, even get to enjoy a life outside of work.
Imagine doubling your output while keeping your costs steady—or maintaining your output while slashing costs by more than half. That’s the potential AI offers.
Are banks positioned to take advantage?
In a survey of 200 senior payment professionals, we found over half of banks plan to use AI to meet payment modernization deadlines for SEPA Instant and ISO 20022.
Banks believe AI can improve the quality of outputs by reducing human error, bridging the expertise gap between subject matter experts, speeding up work, and reducing costs.
And for those with advanced AI expertise, the benefits are even greater—they report more confidence in AI’s ability to deliver long-term strategic value and enhance payments expertise. AI can remember every question asked of every expert from every system. Forever. The risk of brain drain is removed.
The trouble most financial institutions report is that they don’t have the expertise to implement AI solutions on their own. Yet.
Meanwhile, the larger banks are investing huge resources into AI, improving their processes and pulling further away into the distance. The gap between the top of the market is set to widen dramatically.
That said, AI adoption isn’t without challenges.
Banks are rightly cautious about a number of key issues. User expertise is a top concern, as are data quality and security risks.
So, how do banks strike the balance?
By keeping humans at the heart of AI.
Large language models do not have to be tuned for speed; they can be tuned for accuracy. Documents can be checked, reviewed, and published by AI agents, and then signed off by people.
Human-to-human Q&A can be captured from emails, chats and calls; proprietary knowledge doesn’t have to walk out the front door every evening. The productivity and time benefits are enormous.
By implementing AI in a thoughtful, strategic way—investing in people, training and ensuring that teams understand when to trust AI and when to intervene—banks can safely unlock the full potential of AI to revolutionize payments.
Payments modernization can be complex. But with AI, banks can tackle it faster, smarter, and more cost-effectively, all while improving the quality of their work and building a stronger long-term strategy.
If you’d like to know how AI can support your payments modernization journey, speak to RedCompass Labs today.
AnalystAccelerator.ai – AI for payments modernization
Reduce manual work on your payments modernization projects by up to two-thirds (68%) with AnalystAccelerator.ai. Regulatory and project documentation updates that used to take weeks can be completed in under a day, saving banks millions of dollars and months of work.
In trials with a tier one bank, AnalystAccelerator.ai reduced the time it took to create business requirements for the new SEPA Instant Payments Regulations from the standard 25 business days to 45 mins with two hours for human review and edits, delivering a 99.5% time-saving. This helped the bank to get back on track to meet the regulatory deadlines.
Learn more by visiting the AnalystAccelerator.ai website.