Article
6 min read
Why payments needs applied AI
We need SLMs steering LLMs to build new payment flows

Payments modernization is still manual. AI can change that, but only if we can prove it.
Canada is in the midst of a significant overhaul of its payments infrastructure. The Real-Time Rail completed user acceptance testing in Q1 2026. In Q2, two workstreams are running in parallel: Non-functional testing and preparation for Industry Testing and Operational Readiness.
Alongside this, the Retail Payments Activity Act is opening up competition in Canada. And Open banking legislation is moving from policy to implementation. Scheme deadlines are no longer theoretical.
This is not just a Canadian story. Across North America, payments modernization is accelerating. In the United States, the FedNow Service has over 1,500 participating financial institutions less than three years after launch. The Clearing House’s RTP network recently set new records of over 2 million transactions in a single day and $8.36 billion in single-day value. The volume of technical delivery work required to support this wave is enormous.
Despite the scale and urgency of these programs, the delivery lifecycle itself remains extraordinarily labor-intensive. Many banks have mature tooling. But the work of moving from requirements through to tested, validated, production-ready output still depends heavily on manual effort at every stage. The handoffs between phases, the traceability gaps between requirements and test coverage, the volume of review, rework, and reconciliation: that is where the person-hours and the cost accumulate.
AI is already embedded in how Canadian financial institutions approach fraud detection, credit scoring, and customer personalization. According to KPMG Canada’s 2025 GenAI Business Survey, over 90% of Canadian financial services leaders view generative AI as critical to competitive advantage. Banks are rapidly moving beyond pilot projects.
But most of the AI conversation in payments concerns products and customer-facing services. Very little of it addresses the delivery lifecycle itself: the requirements analysis, testing, configuration validation, and code generation that actually build and ship the systems and capabilities.
Even where AI is being applied to technical delivery, there is no widely accepted way to measure its contribution. How much of a given program was delivered by AI versus manual effort? Almost nobody has a credible answer.
Without one, AI in delivery stays in the category of innovation theater. It never reaches the business case. And with transformation budgets under pressure across the industry, proof matters more than promise.
Why does this matter now? RTR timelines in Canada, FedNow expansion in the US, SEPA Instant in Europe, and ISO 20022 deadlines globally: the window for doing things the old way is narrowing. Programs need to move faster, at lower cost, with fewer defects. The question is not if AI will make a material impact (it already is). The real focus now needs to be on how the industry makes the role of AI credible, measurable, and tied to real business outcomes.
At this year’s Payments Canada Summit (May 5–7, Toronto), a panel of senior technology leaders from across Canadian banking and payments infrastructure will take on this question directly. The session, part of the AI Deep Dive day on May 7 (11:10 a.m. to 12:00 p.m. ET), will explore where AI is making a real dent in the delivery lifecycle, where it is falling short, and what it would take to make its contribution credible inside a bank. It is a must-watch if you are attending.
Share this post
Oliver St-Clair Stannard
VP of Payments AI Strategy and Go-to-Market, RedCompass Labs
We need SLMs steering LLMs to build new payment flows
What vendors, banks and systems integrators must do next
Nobody wants to say it: payments complexity exceeds...
Institutions have a short window to get ahead of market, technological and regulatory changes
Most payments modernization projects overrun, go over budget, and fail to deliver to the original spec.
Over half of banks have delayed or scaled back a project.
The articles you read, shared, and talked about most this year

Payments are evolving faster than many banks can respond
The gap between what banks need and what their payments platform delivers
Why does this happen?
From Open Banking and stablecoins to fair fees and faster access
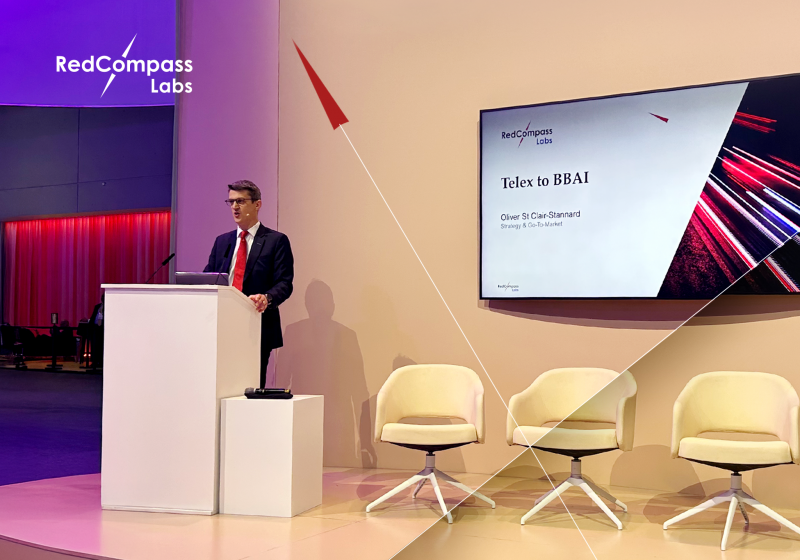
We once trusted humans to type payments over telex.
The payments modernization is plagued by four systemic issues.