If 2024 was about preparing for change in payments, then 2025 was the year the change arrived.
Verification of Payee went live in Europe. So did Instant Payments. Both FedNow and the Real-time Payments Network broke records in the US. Canada’s Real-time Rail edged closer to completion. ISO 20022 crossed a major milestone. Stablecoins became a mainstream topic. And throughout it all, the pace never slowed.
As the year comes to a close, we’ve pulled together the biggest topics of 2025. These are the five stories you engaged with most. The ones that shaped conversations, strategies, and priorities throughout the year. We hope you enjoy them (again).
5. Verification of Payee arrives in Europe: 6 big lessons
Kicking off at number five is one of the hottest topics of the year: Verification of Payee (VoP).
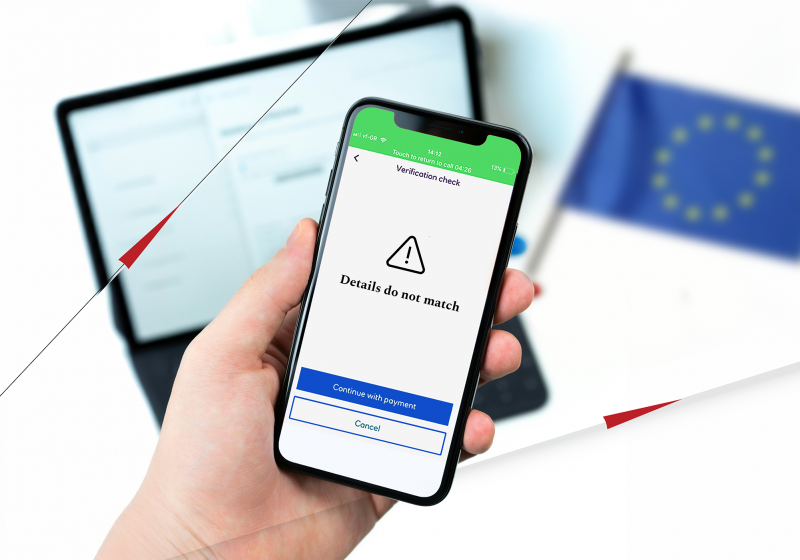
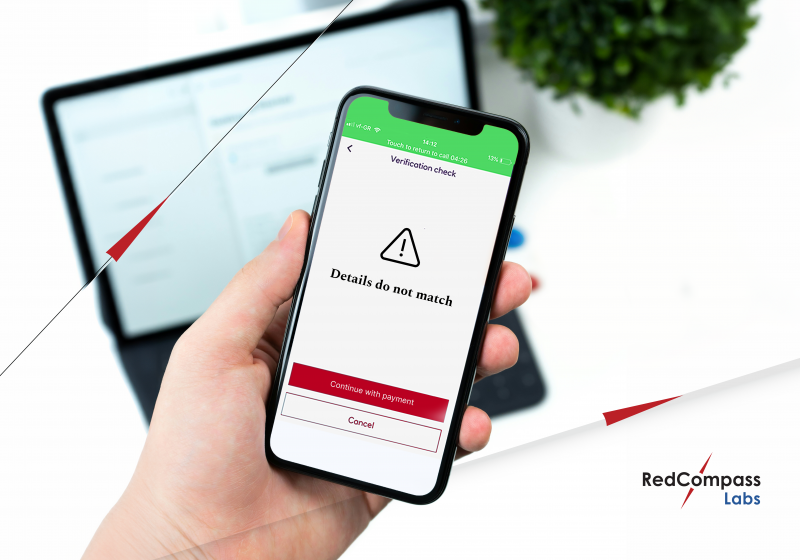
VoP is a digital identity check that confirms the payee’s details before a transfer is sent. If the name and account don’t match, the payer receives a “close match” or “no match” alert, giving them a chance to amend or cancel the payment.
It’s one of the most effective defences against authorised push payment fraud. So effective, in fact, that VoP is now mandatory for both classic and instant SEPA credit transfers across the EU.
When the new rules landed in October 2025, we shared six major lessons from helping banks through the rollout.
You can read them here: Verification of Payee has arrived in Europe: 6 big lessons.
4. Inside Europe’s race to instant payments
Next up is the European Instant Payments Regulation (IPR), another huge topic of 2025.
The regulation requires banks to send and receive instant payments in 10 seconds or less, perform daily sanctions screening, implement Verification of Payee, and charge no more for instant payments than for traditional SEPA credit transfers.
In January, banks faced the first deadline (receiving instant payments). In October, they hit the second: sending instant payments, as the IPR and VoP deadlines went fully live. The shift required a major technical overhaul for many institutions.
Back in March, we asked 300 senior payments leaders how prepared they really were. The findings were eye-opening.
You can download the report here: Inside Europe’s race to instant payments.
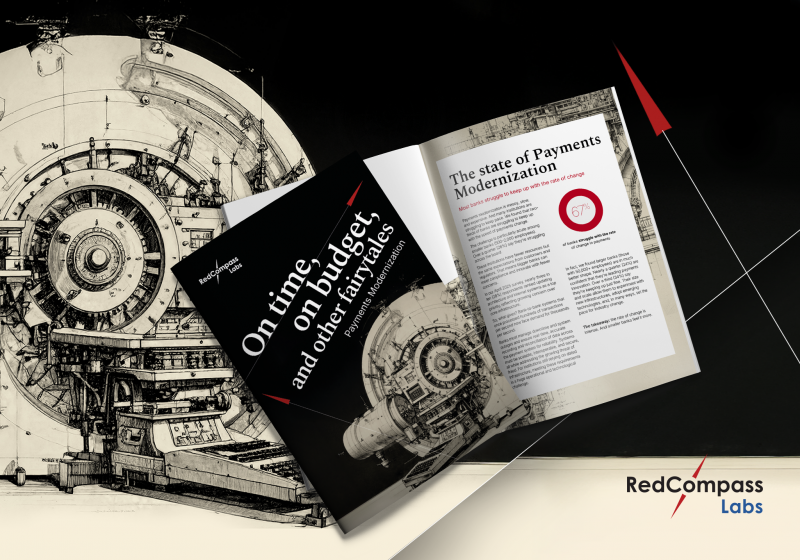
3. Payments modernization: On time, on budget… and other fairytales
In third place is our deep dive into the realities of payments modernization – and why so many programmes struggle.
We uncovered four major challenges:
- The rate of change is relentless (and accelerating)
- There’s a gap between what banks need and what payments platform vendors offer
- Smaller banks risk being left behind
- There simply aren’t enough payments experts
The results are intriguing. Despite most banks saying they’re satisfied with their current vendor, 84% plan to switch providers in the next five years, and nearly half expect to do so in the next two.
The report launched in late September 2025, and the insights remain just as timely.
Get your copy here: Payments modernization: On time, on budget, and other fairytales
2. Will the ISO 20022 coexistence period really end this year?
At number two is a big question for the year: Is the ISO 20022 migration really ending?
In November 2025, Swift officially ended support for sending both MT and MX payments messages via its network. From this point forward, only MX messages are accepted, marking “the end of coexistence.”
But this isn’t the end of ISO 20022. Far from it.
There are major changes to Exceptions & Investigations, a wave of legacy processes to update, and one of the biggest challenges yet — structured addresses.
ISO 20022 will keep banks busy well into 2026 and beyond.
You can read more about how here: Will the ISO 20022 coexistence period really end this year?
1. The next big ISO 20022 migration: structured addresses
And coming in at number one is the topic many of you are watching closely: the ISO 20022 structured address migration.
In 2026, banks will need to shift from free-text addresses to fully structured, standardized address formats across payments messages. This is one of the most complex — and impactful — migrations yet.
As a bank, you’ll need to update libraries of messy customer address data. It will affect screening, routing, compliance, KYC, and customer onboarding. Every payments participant will need to adapt.
It’s the next major transformation in the ISO 20022 journey, and clearly the story you read the most in 2025.
You can read it here: The next big ISO 20022 migration: Structured Addresses.
What’s coming next?
Our experts have explored the biggest payments trends of 2026. There are a few you’ll be familiar with, and some you might not have seen. You can check them out here.