In February 2018, a number of Nordic banks published their ambition to create a common Nordic payment infrastructure to meet market needs for efficiency, standardization, freedom of choice, and cost focus. This initiative is called P27.
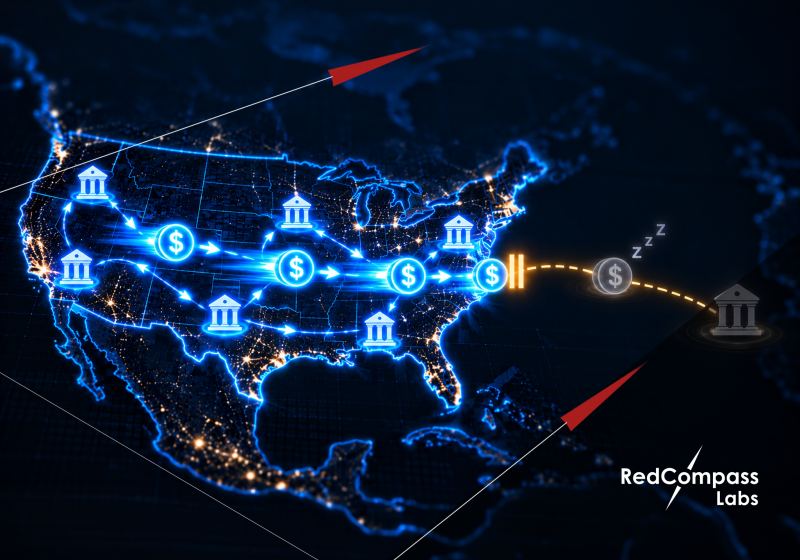
P27, or Project 27, aims to establish a single pan-Nordic payment infrastructure for the 27 million inhabitants of the region. The new payment platform will enable users to make direct payments between different currencies across national borders of Nordic countries and transform the way money flows for consumers, businesses, society, and the payments industry at large. This will be a world’s first and create the foundation for multiple initiatives and innovations in the Nordics.
The banks that form the P27 Group are Danske Bank, Handelsbanken, Nordea, OP Financial Group, SEB, and Swedbank. The intention is to replace the several platforms that currently exist to create real-time, batch, domestic and cross-border payments across the Nordic countries of Finland, Denmark, Sweden, and Norway.
P27 will kick off with Sweden domestic batch payments release as of today, followed by the instant payments – but don’t be surprised if you see otherwise in a few months 😉.
The target for cross border payments seems to be far away and it needs to be seen how P27 and Nordic banks approach it. As of today, Norway is not part of the current scope, and in the meantime are working towards upgrading their own local clearings.
Once P27 hits the Nordic market, the local platforms will be decommissioned gradually, and the payment volumes will be combined into one Nordic payment platform.
This will create a real-time view of the multiple systems running and a better view of user information, balancesm and data between the systems that can eventually generate new revenue opportunities.
Undoubtedly the local formats will be replaced by ISO 20022, that will be used for the next-generation of payment services, not just in the Nordic region, but also in the European Union and beyond. So, in the longer run, moving to standard payment processing software to automate payment processes will reduce costs in the form of payment processing, thus helping businesses to focus on core business activities instead.
A single integration point will allow banks access to a wider range of services that they would otherwise need to integrate to separately or simply avoid. Gaining access to these services will also allow banks to migrate away from some of their costly and time-consuming legacy infrastructure in exchange for a modern fit for purpose service architecture.
P27, Sweden release and Swish
P27 is currently in a phase where they are moving from prospective participants to actual customers for testing their solution and first in line are 13 banks connected to Getswish AB, the dominant instant payment solution in Sweden, and also the company behind Swish, an instant payment app that boasts more than 8 million users in a country of 10 million people. Whoa that’s something!
The major focus remains to be Sweden now for its first release in Nordics. The current timeline calls for SEK (Swedish Krona) batch preparations to be finalized during the second half of 2023, followed by SEK instant preparations to be finalized in early 2024.
Banks connected to Swish are set to test the Nordic payments platform by the end of the year and, starting in 2023, P27 will process all Swish payment flows. Currently the major challenge is Swish’s e-commerce market, which accounts for around 20 percent of the market share. Despite the pandemic boost and Swish being the preferred payment method for Swedes, not all merchants offer payments via Swish today. So, the P27 participating banks have their agenda cut out and are working together to close out this gap.
Nevertheless, while Swedish banks may be the first to join P27’s platform, their Danish counterparts aren’t far behind. An active transformation committee has already been set up in Denmark to facilitate the transition towards P27.
P27 and merger of mobile wallets
As Swish works with its peers across Europe and partners with international banks to grow the service, a consolidation trend in mobile payments is underway in the Nordics. The mobile payment providers Vipps in Norway, Pivo in Finland, and Mobile Pay in Denmark, have agreed to merge. Here, P27 will help to minimize the impacts in terms of costs and timescales. The proposed merger of the main mobile wallets in Norway, Denmark, and Finland creates the possibility of a pan-Nordic wallet with more than 11 million users and more than 330,000 merchants across the three countries. Until the merger is complete and implementation plans are finalized, it is impossible to know exactly what the shape of the technology will be, but it seems reasonable to assume that users of the new Nordic super wallet from one country will be able to use it in the other countries. Enabling this kind of cross-border, pan-European payment infrastructure is exactly what P27 was built to support. By providing the rails for the underlying account-to-account infrastructure, P27 would be ideally placed to allow banks that are already connected to P27 to rapidly onboard to accept, clear, and settle cross-border payments in the Nordics. In the future it is easy to imagine the scope of the new wallet expanding to outside of the Nordics. Quite a revolution, isn’t it?
P27 and Instant payments
P27 also has its major focus on instant payments and the need to ensure systemic resilience moving forward. A big chunk of their budget is invested in this initiative. They believe a modern instant payments infrastructure distributed across data centers in the Nordic countries will significantly improve the resilience and security of retail banking systems in the region.
Propelled by Nordic central bank alignment around TIPS and the growth in instant payments, P27 will be able to offer Nordic banks full reachability across the eurozone.
The Danish central bank’s move to include the DKK (Danish Krona) in the European Central Bank’s real-time settlement system TIPS, followed by a sector decision to move to P27, was another important development in P27 arena.
P27 and CBDC
P27 also have their eyes and plays on the ever-evolving topic of CBDCs (Central Bank Digital Currencies). Regardless of how the eventual CBDC solutions in or across the Nordic countries are designed, the P27 infrastructure is being designed to adapt these transactions, support the transmission of messages and reconciliation of value. The fault-tolerant, high-availability architecture that P27 offers makes it an ideal network to support CBDC use cases. The use of the P27 infrastructure for value exchange beyond monetary value means that it, over time, potentially can be extended out of pure CBDC offerings into wider use cases under asset tokenization, where the wider digitization of assets means the ownership of these can be fractionalized and then transacted upon.
P27 and large and small Nordic banks
P27 also has their focus on levelling the playing field between large and small banks in the Nordics region.
They have plants to democratize access to new services and capabilities by making it easier for smaller banks to have the same reach as larger banks.
P27 is an opportunity for regional banks to develop their own cross-regional services on top of the basic rails. Services can be fine-tuned for both individual banks, specific countries, and for the entire region in a way that would not be possible when dealing with a European or global scheme.
In addition, P27 will make it possible for banks in Germany or the Netherlands to settle payments in Nordic currencies. This will enhance the value of the Nordics as an integrated payment region where it’s easier to do business.
P27 is undoubtedly one of the big things happening in the Nordics payments world today, and they have their plans to accommodate most of the upcoming trends in the payment’s world. At the same time, the banks seem to be excited about P27 and have started due preparations to meet the timelines, but its near future impact in the Nordics market remains to be seen with the Sweden release.
However, the following questions remain unexplored:
- How the Nordics central banks will be involved during P27 cross border release?
- What are the relations between the big founding banks and the smaller banks? Are the smaller banks really as keen as P27’s PR pitch describes? Are there some frictions already? What is the consequence if a bank doesn’t want to join? What is the impact of this being organized by small number of banks compared to the EPC which has 77 PSP members?
- ‘P27 will make it possible for banks in Germany or the Netherlands to settle payments in Nordic currencies.’ Why Germany and Netherlands only and why not whole SEPA?
- What is the scope of ‘Swish’ with respect to P27 in the future?