Article
6 min read
The hidden cost of ISO 20022 messages
Migration was only ever the first invoice

Over the next five years, as central banks across the globe upgrade their settlement platforms to handle ISO 20022 financial messaging, the banks participating in these settlement networks will have a massive workload on their shoulders.
Testing these changes will be extremely challenging and critical for banks. Many of their internal processes and daily operations will be impacted, yet these changes must result in no adverse impact to their customers. So, how should banks plan for ISO migration testing?
At the end of July, the European Central Bank announced its decision to extend the timeline of the TARGET2 and TARGET2-Securities consolidation project to November 2022. The decision was driven by several factors, including the impact of COVID-19 and the postponement of the start of SWIFT’s ISO 20022 migration. Until the migration period ends in November 2025, all major clearing platforms globally will be upgraded, and banks across the globe will deal with a near-constant cycle of change as ISO 20022 messages start to ripple out across the global SWIFT network.
Due to the sheer volume of change banks will experience during this ISO 20022 migration, the ability to test end-to-end payment processing effectively, efficiently and quickly is critical. Payment messages, and the data they carry, flow through a complex end-to-end payment processing chain within each bank’s systems, including various customer channels, a payment engine, numerous transaction filtering and monitoring systems and the core banking platform.
When defining their testing strategy for ISO 20022 migrations, banks should first and foremost consider the coverage as the scope of change is enormous. The number of scenarios they will need to validate to avoid any customer and operational impact is tremendous, wider than any regulatory projects implemented in the last 10 years, including SEPA.
There is also is a greenfield aspect to consider as banks will not really be able to anticipate the exact MX message that they will receive. While, of course, there are standards implemented to guarantee that the same practices are followed, there is still room for creativity! (We are very eager to see how some Russian payment specificities will be conveyed in the MX format) Banks will need to create lots of variances to really validate that a given business scenario works in production.
Unfortunately, today’s standard test automation frameworks cannot rapidly test vast volumes of changes in a short period without test costs spiralling upwards. Some of the challenges include:
So, how can banks overcome these challenges? The answer lies in using advanced data analytics technologies, including machine learning and data science techniques.
In order to face the challenges presented by the ISO 20022 migration, banks must increase their capacity to process and analyse high volumes of test cases in a short period of time. To do so, they need solutions that combine efficiency and accuracy while making sure that their costs don’t spiral.
Concerning improving test coverage, a first crucial step is understanding how customers and correspondents will provide the payment information. Machine learning is key to this analysis. It offers insight to:
Furthermore, machine learning can execute the first level of testing triage by analysing millions of payment scenarios, automatically comparing payment behaviours between the legacy and target systems and then grouping and classifying the differences. Using this information, downstream Quality Assurance analysts can effectively, efficiently and quickly identify and document defects, as well as confirming expected behaviour.
By applying these concepts to their ISO 20022 testing strategy, banks can drastically reduce the duration of their testing cycles, while improving their confidence to go live, enabling them to handle the tsunami of change heading their way.
RedCompass Labs teams are already using this data-analytics led testing approach with our clients, combining our QA expertise and big-data analytics experience to dramatically amplify testing capacity. By cleansing and comparing existing production data, we have cut the time and number of people required for testing, increased coverage, and significantly improved quality and confidence for go-live.
Share this post
RedCompass Labs
You may also like
Resource
ISO 20022 Migration: 5 must-haves for success
Wondering how banks can ensure a timely and successful migration? Download the "ISO 20022 Migration: 5 must-haves for success" whitepaper.
Download now
Migration was only ever the first invoice
Postponing by two weeks gives T2’s address rules a grace period, not a rewrite
Not so long ago digital money was written off as a niche experiment, irrelevant to mainstream…
Gated content
SR 2026 has been postponed until 2027
MT 101 is ending. Here’s what to do before the switch to pain.001
Everything you wanted to know about E&I, but wasn't covered in our webinar
Banks have until 2027 to move exceptions and investigations to ISO 20022
The clock is ticking...
Gated content
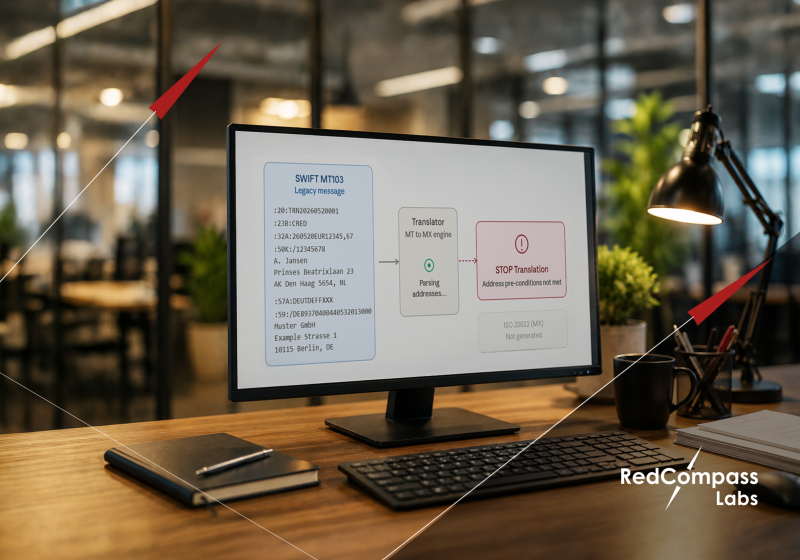
Fully unstructured addresses will be phased out in November 2026
Missing the deadline has wide-ranging consequences for the banking industry
Meeting new data, messaging and operational demands
Europe's payment engine is taking a major step towards ISO 20022 alignment.
Banks face two major ISO 20022 deadlines in 2026. Will they meet them?
Fedwire, CHIPS, and Swift (CBPR+) are all moving on the same timeline.

Payments are evolving faster than many banks can respond
Gated content
Here's everything you need to know about ISO 20022 for the foreseeable
Think your ISO 20022 journey is almost over? Think again.
Gated content