Designed by the Federal Reserve, FedNow will be the first new payments rail in the United States since the Automated Clearing House (ACH) was introduced in the early 1970s.
Following almost a decade of development, this July the first phase of FedNow was launched, with 35 banks and credit unions, and 16 payment-process service providers taking part. This stage offers baseline functionality for various use cases, including account-to-account transfers and paying bills. In 2024, a more formal, wide-scale release is planned, with subsequent phases adding new functionalities.
A deeper dive
While services like PayPal, Venmo and Zelle are already revolutionising the world of instant, person-to-person payments, FedNow’s mission is to increase accessibility, efficiency and widespread adoption from regional banks, too.
To this end, it has created an instant settlement and clearing service for online payments. This means that the banks on either end of the transaction can instantly exchange associated information and move money between relevant customer accounts. This service will be, in some ways, like the Real-Time Payments (RTP) network from The Clearing House (TCH). However, these two systems differ in how they access interbank liquidity and confirm settlement at the recipient accounts.
FedNow leverages participating banks’ existing master accounts at the Federal Reserve, while the RTP’s rail requires participants to have a separate pooled account for liquidity with TCH. With the RTP’s rails, interbank settlement happens prior to the RDFI (the bank where the recipient’s account is), confirming the existence and the standing of the recipient’s account. On the other hand, under FedNow, interbank settlement will come after the RDFI has confirmed the recipient’s account information.
Some of FedNow’s other key capabilities include:
- Instant payments – 24/7/365
- Core clearing and settlement capabilities
- Support reports, queries and manage configuration
- Settle their own master accounts and COR master account
- Credit transfer use cases (account to account and bill payment)
- Configurable transaction limit and network limit
- Rich data supported within ISO 20022 messages (including remittance information)
What does it mean for SMBs?
Aside from consumers, this new system is likely to benefit small and medium-sized businesses (SMBs) the most.
SMBs can leverage FedNow’s real-time payment capabilities to improve cash flow and reduce the risk of late payments. For example, a small business can use FedNow to immediately receive payments for products and services rather than waiting for a cheque to clear or a wire transfer to be processed.
They can use FedNow to offer their customers a more convenient and seamless payment experience. Accepting real-time payments from customers reduces the need for paper cheque or manual payment processing.
FedNow can also streamline accounts receivable processes, enabling faster and more efficient payment processing. This can help SMBs reduce the amount of time and resources they spend on payment collection and reconciliation.
SMBs can better and more efficiently manage their cash flow, as FedNow provides real-time visibility into their account balances and transactions. This, in turn, means that they can make more informed decisions about spending and investment strategies
But what’s the point?
You might be thinking, “If the US already has real-time payments through TCH, then why do we need FedNow?” To that, we say, technically yes, FedNow isn’t offering anything we haven’t seen already, as the RTP network already offers instant payments, albeit via a private network. But this isn’t a zero-sum game. It’s the way that FedNow is offering its new service that could make all the difference. And the combination of both could also be positive for both consumers and banks.
Here are some more reasons.
- As both FedNow and RTP support ISO 20022, there are high chances of interoperability in future.
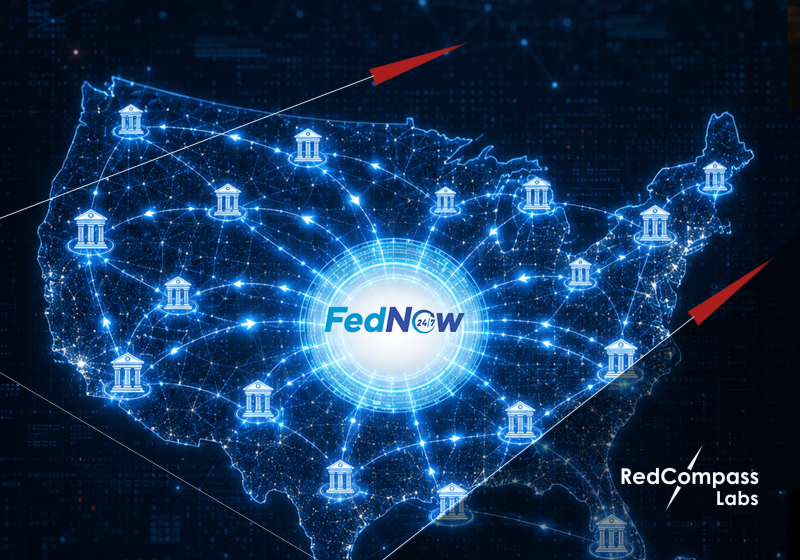
- In addition, RTP reaches 65% of demand deposit accounts. In total, there are 274 participating banks and credit unions. FedNow, on the other hand, will be linked to the Federal Reserve’s FedLink Network, which already serves 10,000+ financial institutions.
- The network coverage by FedNow would allow universal accessibility of instant payments across all banks and credit unions in the US, including smaller financial institutions
- Additionally, it future-proofs the US by allowing it to bridge the payment technology gap that exists when compared to other countries
- With FedNow, you don’t need set up your separate master account with FED, you can use your existing FED account for FedNow settlements, liquidity and position tracking.
Where’s the catch?
This is not to say it’s all going to be smooth sailing. Some critics say FedNow will end up competing with private-sector companies, while others counter that it’s just going to end up as an expansion or additional service.
There are also, as with any instant payments systems, worries over fraud. With fast processing time comes less time to stop bad actors. Meanwhile, others argue that the ability to move such large sums, even though there is a limit at present, could introduce instability into the banking system.
As with any significant change in a complicated ecosystem, it can’t all be good news – but, on the whole, FedNow will bring the United States more in line with the rest of the world’s move towards instant payments. And that can only be a good thing.