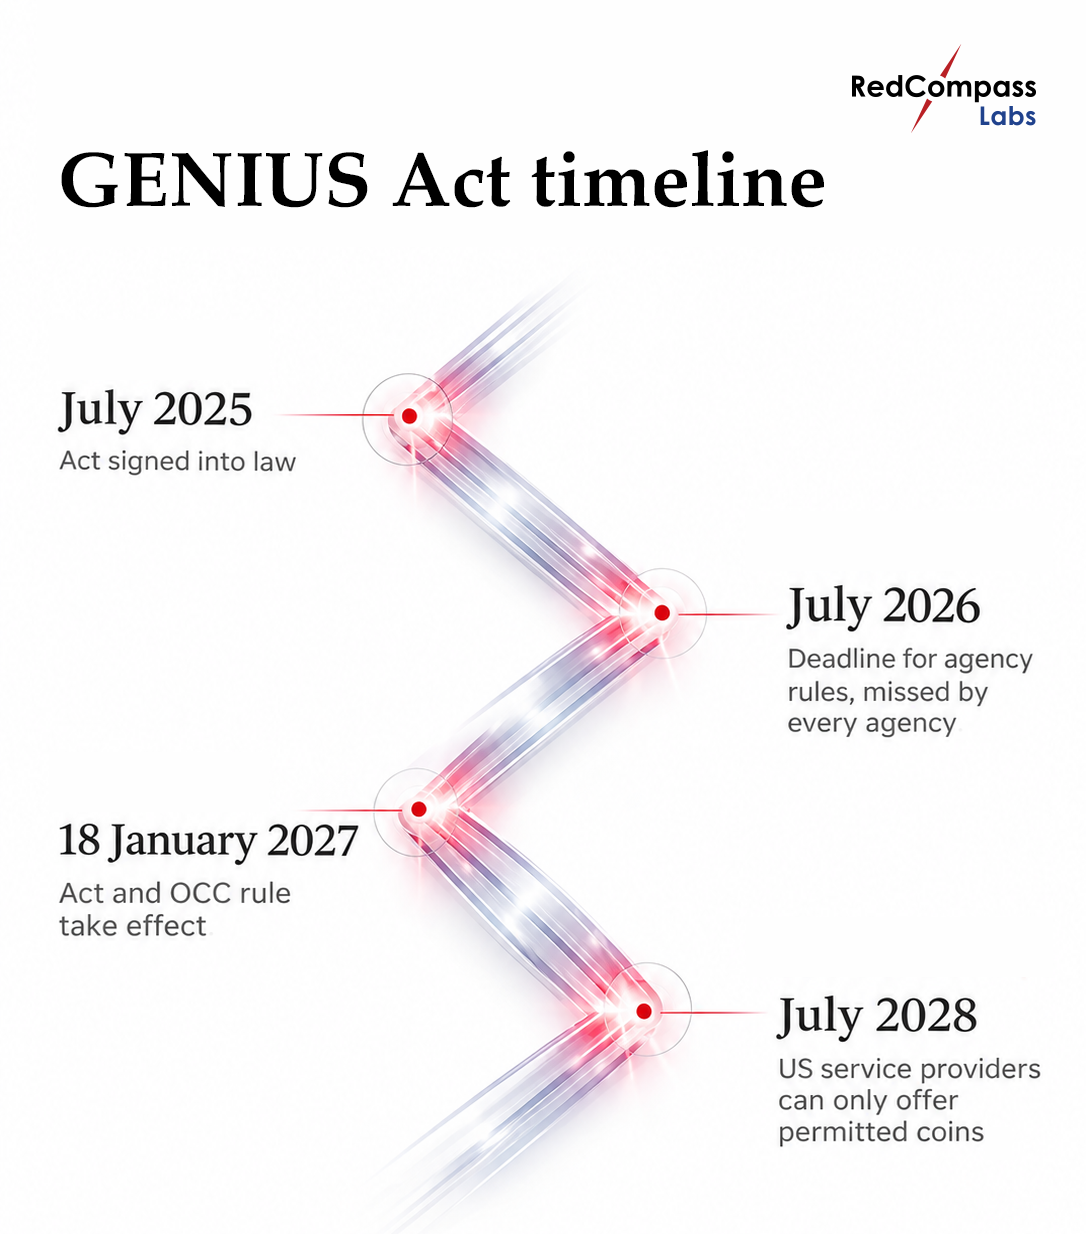
In July 2025, the GENIUS Act was signed into federal law. The first of its kind for dollar stablecoins.
US regulators were given one year to write rules for the issuers they oversee. They all missed the deadline.
Then, on 21 October 2026, the first rulebook arrived. The Office of the Comptroller of the Currency (OCC) published its final rules, covering reserves, redemption, custody, and risk management.
There’s a lot of excitement and confusion about what it means. So we’re here to clear things up.
This is what you need to know.
Who’s writing the rules?
Let’s start with how this works.
In the US, a law says what must be done. Rulebooks, written afterward, say how it will be done.
It’s a bit like building regulations. The law says who can build a hospital and where. The regulations (aka the rules) explain how high the ceilings can be, how many fire alarms it needs, what emergency power it must have, and so on.
The GENIUS Act is the law. Several regulators now have to write the rules, each covering different issuers:
Office of the Comptroller of Currency (OCC): oversees national banks and their subsidiaries, federal savings associations, federal branches, non-banks that it licenses, foreign issuers, and some state issuers. It also covers stablecoin custody at OCC-supervised firms.
Federal Deposit Insurance Corporation (FDIC): looks after state-chartered banks that aren’t Federal Reserve members.
Federal Reserve (the Fed): has its member banks.
Treasury: Has its own issuance rules, plus anti-money-laundering and sanctions rules, written with the OCC.
The OCC is the first to finish. Its rule doesn’t cover issuers under state-chartered banks, which fall to the FDIC or the Fed. So for any bank, the first question is a structural one: which charter would our issuing entity sit under?
What the GENIUS Act says
Only a licensed issuer can issue a payment stablecoin to people in the US. There are three routes:
Bank route: a subsidiary of an insured bank, approved by the bank’s federal regulator.
Federal non-bank route: a non-bank licensed directly by the OCC.
State route: a state issuer with under $10bn of coins outstanding, under a state regime judged comparable to the federal one.
Large public companies that aren’t financial firms, like big tech, can only issue if the Stablecoin Certification Review Committee votes unanimously.
The Act also sets six rules. It’s the agencies’ job to say how issuers meet them:
1. Reserves backed 1-to-1
For every $100 in coins, the issuer holds $100 in high-quality assets: cash, bank deposits, Treasury bills with maturities of 93 days or less, repurchase agreements, and money market funds that hold those assets. Reserves can’t be lent out or reused, with narrow exceptions.
2. Monthly transparency
The reserve mix is published monthly and examined by a registered accounting firm.
3. No interest or yield
Issuers can’t pay holders interest or yield. How far that reaches partners and exchanges is the live fight.
4. Holders paid first
Reserves sit outside the issuer’s insolvency estate, so if the issuer fails, holders have first claim on the reserves, ranking ahead of other creditors.
5. Bank-grade financial crime controls
Issuers are financial institutions under the Bank Secrecy Act. They need full anti-money laundering and sanctions programs, and must be able to freeze and seize coins on lawful order.
6. A payment instrument, not a security
Stablecoins can’t be marketed as government-backed, legal tender, or deposit-insured.
Why 18 January 2027?
The Act takes effect on the earlier of two dates: either 18 months after signing, or 120 days after the final rules are published. The OCC published on 21 October, so 120 days would land in mid-February 2027. Eighteen months comes first, and the OCC’s rule applies from the same day. From then, issuing a payment stablecoin in the US without a GENIUS Act license isn’t allowed.
Why July 2028?
From that date, US digital asset service providers, meaning exchanges, custodians, and wallet providers, can only offer coins from permitted issuers. That squeezes out unlicensed coins, which is a real question for offshore ones such as Tether’s USDT.
Five changes in the final rule
The OCC kept the Act’s safeguards but relaxed the requirements for meeting them.
Area
February proposal
October final rule
Rewards via partners
Presumed to break the yield ban unless proven otherwise
Presumption dropped. Potential rule breaches will be reviewed on a case-by-case basis
Liquidity
10% of reserves available daily, plus weekly and maturity limits
5% daily. Weekly and maturity limits dropped
Concentration
No more than 40% of reserves at any one institution
40% per counterparty. US government, custodians, and cleared repurchase agreements excluded
Redemption
Automatic 7-day extension for large redemptions
Payment started within two business days. OCC told within 24 hours if requests exceed 10%
Capital
More complex capital elements
$5m minimum, plus 12 months of expenses as a backstop
The proposal said that if an affiliate or third party paid rewards to holders, that was presumed to break the interest ban. That presumption is gone. Supervisors will look at how each reward is funded and why it’s paid. The ban on the issuer paying interest itself remains in effect. The American Bankers Association reads the result as leaving room for economically equivalent yield.
The two-day clock runs from receipt of the request to the start of the payment, not to the customer receiving the money. If requests in a day exceed 10% of the coins, the issuer must notify the OCC within 24 hours and may request more time. There’s no automatic pause.
And up to half of the 12-month expense backstop can be qualifying debt, so at least half is equity.
What banks can do
There are four realistic roles for a bank, and they can be combined. For most banks, issuing a stablecoin alone isn’t the right move.
Issuing. A bank can issue its own stablecoin through a subsidiary. The economics are better after the final rule, but there’s a catch. The deposits most likely to move into a bank’s own coin are its cheapest and stickiest ones. Issuing turns money the bank can lend into reserves it can’t lend. For most banks, that makes it a cost, not a source of profit.
Partnering. A bank can provide the banking layer for an issuer or an exchange, meaning the accounts and cash settlement. Citi has announced this kind of partnership with Coinbase, though it isn’t live yet.
Serving issuers. A bank can hold an issuer’s reserve deposits or act as its custodian. It can also convert deposits into coins and back again. That earns fees using things banks already have, such as know-your-customer checks and payment systems.
Tokenized deposits. The OCC rules say that a bank deposit held on a digital ledger isn’t classed as a payment stablecoin. So they stay insured, they can still fund lending, and they can still pay interest, which a stablecoin can’t. They also don’t need a new issuer or a redemption regime. That makes tokenized deposits the most direct way to respond if exchanges or fintechs start offering rewards.
Four things to do before 18 January 2027
The first step is to size the exposure. Work out which groups of depositors would move their money if an exchange or fintech offered rewards on a stablecoin.
The second is to choose a position: issue, partner, serve issuers, offer tokenized deposits, or a mix.
The third applies if you issue or partner. Test how you’d handle redemption within two business days at stressed volumes, across both treasury and payments. There’s no automatic pause anymore, so this is a real operational requirement.
The fourth is to map which charter and regulator would govern the issuing entity. Then keep track of the final rules from the FDIC, the Fed, and the Treasury.
This is a starting point for discussion, not a recommendation for a specific business model.
The OCC’s rulebook is the first, not the last. And the question remains: what happens to rewards?
Are banks actually ready for stablecoins?
Our latest research found that banks are building for every form of digital money, with 72% planning, building, or operating their own-issued stablecoins.
But there’s a big difference between experimenting and building the infrastructure that can handle these new rails.