In the past ten years, extensive progress has been made toward achieving financial inclusion. Thanks to policy innovation and expansion of technology, global account ownership has increased from 51% in 2011 to 76% in 2021. It is a success, but now the financial sector faces a new challenge: low engagement with (and use of) financial services by new users. According to World Bank, in India, over 300 million additional customers have entered the financial sector, but nearly 50% of bank accounts have never seen a single transaction. And while this problem is most recognizable in India, it is an issue in many other countries all around the world. It means that access and inclusion do not necessarily translate into use – and that to achieve robust financial health, using financial services is the ultimate goal.
Importance of behavioral economics
There are challenges on both sides of this issue: customers do not find financial products helpful in building financial buffers and financial service providers cannot sustainably serve the underbanked. Reason? Financial products offered do not take into account the context and needs of the customers.
To change that, institutions and people working on financial inclusion must understand how people (providers and consumers) process information, make decisions and choices, form preferences, and act on their choices. Heuristics and behavioral biases are what affect us most when making decisions. Heuristics are very simple mental shortcuts that we use to make decisions, especially when faced with complex problems. This way of thinking makes us “fall” into errors called cognitive biases. By understanding this, we can make a big step in closing gaps and addressing access to financial services and action. It means changing the communication, presentation, and delivery of service information.
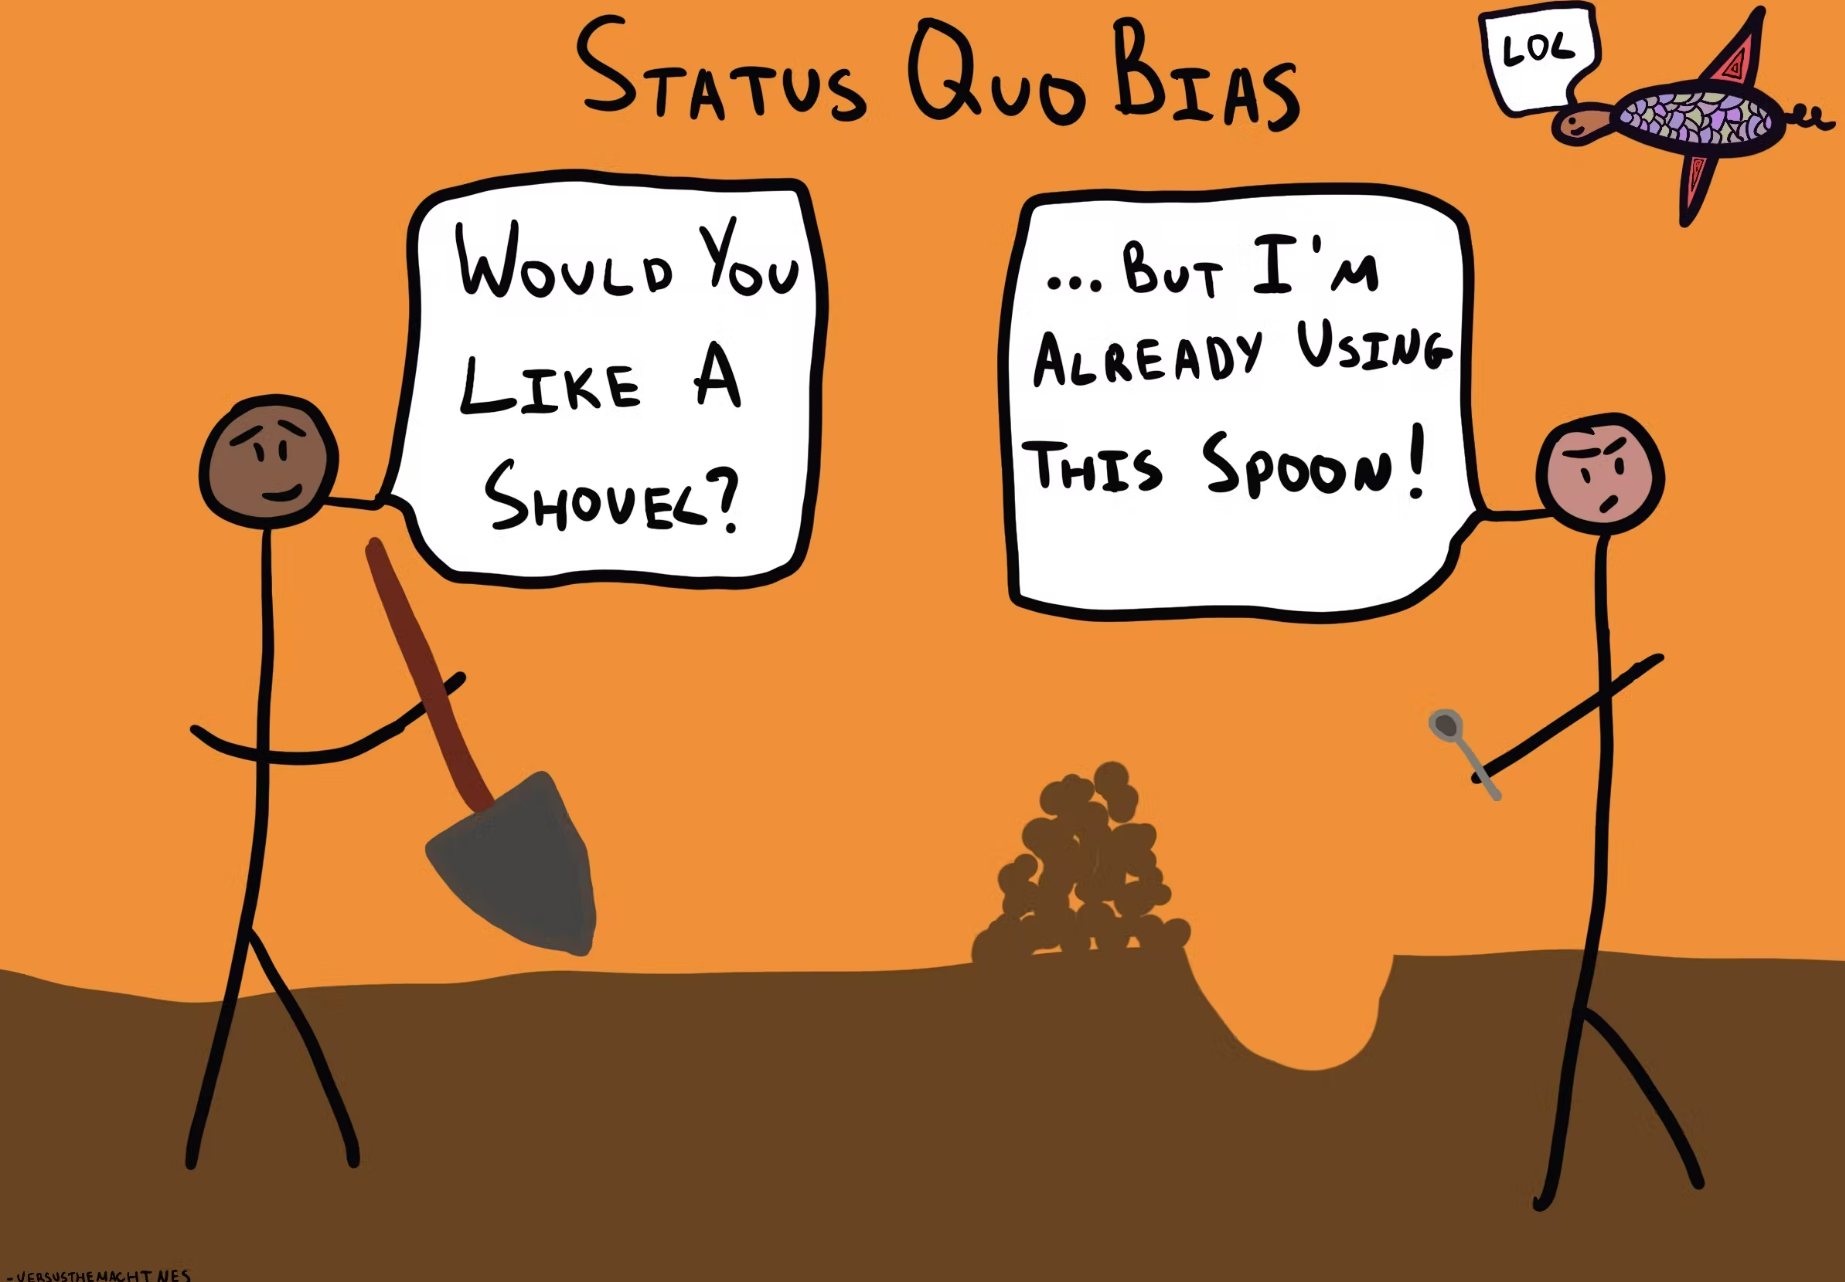
To better understand the concept of biases, we can use the status quo bias as an example. This is a tendency to remain in the current situation. Status quo bias explains why people resist change, even when it would be more beneficial to make that change. We see this in real life when newer alternatives are presented, especially when those alternatives come with more complex information and advanced technology. This, for example, can prevent potential customers from switching from cash payments to digital payments or from visiting local branches to using digital services.
Source: https://thedecisionlab.com/biases/status-quo-bias
Behavioral economics in practice
Boosting underbanked customers’ engagement with financial products is a drop in the sea and the only first step towards supporting their financial health. And even when they sign up for the new product, they rarely use it in day-to-day activities or discover its full potential. This does not mean that they do not want to. Many reasons that can explain this situation evolve around behavioral barriers (such as lack of trust, too advanced technology, too many options). How can financial institutions make use of that knowledge?
Usually, financial service providers focus on growing user engagement with their products through traditional solutions: marketing campaigns, small financial encouragements, or expanding the possible ways users can access the product. However, there are more effective ways to consider the human factor. Some possible solutions include adding human elements to messages, providing signals that build trust in the product through the customer journey – for example, visual clues that confirm outcomes (e.g., transaction completed) – and inform why service providers need sensitive information from customers.
Also, what is very important, is to make the process of making decisions and taking action along the user journey as simple as possible. This can be done by presenting a limited number of options for choosing among plans or features, using simple and accessible language, highlighting essential details, and reducing onboarding steps.
Case Study: Increasing uptake of a digital wallet among women in Pakistan
Financial service providers, despite their intentions, often struggle to target unbanked or underbanked customers. Ideas42 and Women’s World Banking (both non-profit organizations) partnered with a large telecommunication company (JazzCash) in Pakistan that offers digital wallets to their customers. JazzCash overgrew its customer base, but only 10-15% of its customers were women.
To approach this challenge, JazzCash introduced it via SMS messages referral campaign. They conducted A/B testing, including SMS messages sent to women that were the company’s existing customers. All of the people who referred new customers received small financial encouragement. The first part of the SMS messages highlighted this information, the second one did not say anything about encouragement and was written in a gender-centric language (to suggest choosing women as potential referrals).
The first round of tests showed that the most effective were messages with information about financial incentive (7.1%). SMS messages that were framed behaviorally, reached 6.4% and increased new female customer sign-up by around 64% more than the standard marketing campaigns. Those tests show that further focus on behavioral framing may have a similar outcome as a financial reward but be more cost-effective for service providers.
Conclusion
To transform financial inclusion using behavioral science, financial service providers have to understand behavioral mechanisms, but also find a way to adapt them effectively. Including human factors in creating strategies, plans, services, and products (especially in the early stages of development) can improve customers’ financial health and support financial service providers’ sustainability. Behaviorally informed design and minor changes to existing solutions can generate social impact on a large scale. Overall, combining behavioral economics with new technological solutions in financial services can be a very powerful tool that can help open the finance world to all.
Differences in economic standing in each community would affect both inclusion and exclusion in global financial services. Digital remittance contributes to streamlining global financial inclusion. But, when it comes to financial exclusion, in-depth understanding is important.
To understand the extent of impacts, a digital guide The Impact of Global Financial Inclusion & Exclusion: A Data-Driven Exploration of Access to Financial Services could help.