What can banks in the US and Canada learn from UPI?
India is ahead of the game when it comes to instant payments. What could the US and Canada learn?
In our third and final episode on UPI, Pratiksha Pathak compares instant payments in North America to the Indian market.
What can the US and Canada learn from UPI instant payments?
Instant payments haven’t taken off in the US yet. That’s in part because the US economy is card-based. Banks make a lot of money on interchange fees and late payments, which means it’s difficult to sacrifice profitable credit and debit cards for free instant payments.
Banks also usually need to update their architecture to accommodate instant payments, which is costly and time-consuming. And without a regulatory push, as there has been in other countries, there’s no real urgency to do it.
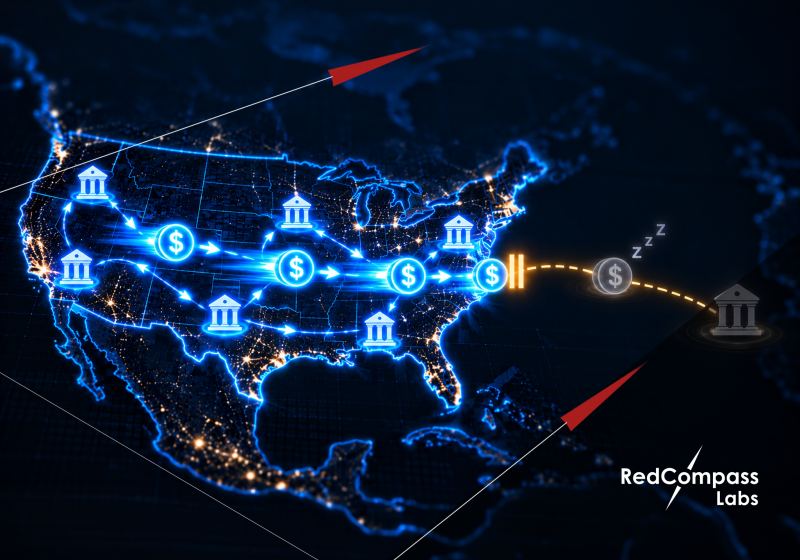
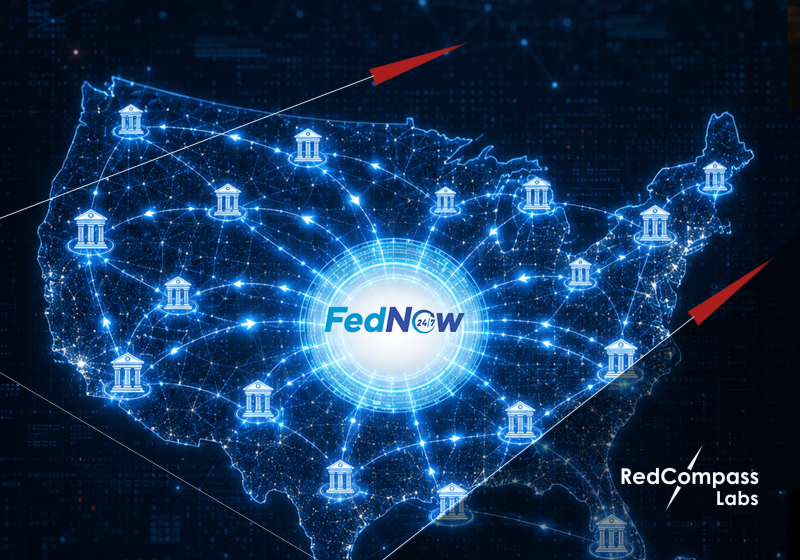
Even if they are on board, US banks have to choose between two instant payment schemes: RTP and FedNow. The schemes are not yet interoperable, which means picking one is difficult, and choosing both is expensive. Some banks are sitting on the sidelines as a result.
Ultimately, US banks want to see demand before implementing instant payments at scale. But without widespread implementation, consumers and businesses cannot demonstrate it.
Meanwhile, Canada is yet to launch their instant payments scheme, the Real-time Rail. It’s expected to go live in the next few years.
Which gives the US and Canada a big opportunity. While neither country has fully adopted instant payments, there are lessons to be learned from the successful rollout of UPI.
UPI instant payments: lessons for the US and Canada
For starters, UPI is interoperable, free, and easy to use.
That means banks don’t need to choose between multiple schemes – they just sign up to UPI and start offering instant payments. It’s easy for consumers and businesses, too, which helps demand.
The openness of UPI has also boosted innovation. Third-party apps like PhonePe, GooglePay, and Amazon Pay use UPI to enhance their product offerings, creating new use cases and driving adoption further.
There have also been several product updates to promote financial inclusion and uptake of the scheme, as well as partnerships around the world – which may soon include the UPI payments in the US.
It’s not all plain sailing – fraud has been an issue. But the US and Canada can learn from UPI’s experience here as well and implement a Confirmation of Payee service as early as possible, to avoid the same fate.
As the world marches towards 24/7 instant payments, the lessons from UPI are crystal clear: the US and Canada must create the right environment for instant payments to flourish.
That means developing an interoperable, free, and easy-to-use instant payment scheme, that fosters innovation and boosts financial inclusivity. At home, and further afield, too.