Article
6 min read
The hidden cost of ISO 20022 messages
Migration was only ever the first invoice

Banks typically use around 70 to 80% of their payment change budget to comply with regulations and industry changes. For example: the annual European SEPA rulebook and global SWIFT upgrades, the multi-year ISO 20022 migration, or in the UK the implementation of Open Banking and the New Payment Architecture.
With only a small portion left for innovation and initiatives that deliver strategic business outcomes, how can banks possibly compete for the future? Today, we want to share with you some tips on how to get the most value from your regulatory change programmes.
We often hear banks complain, “How can I innovate when the majority of my change budget is allocated to compliance with regulation?”
The truth is: innovation is not optional for banks who want to survive. However, various incumbent banks find themselves carrying a huge Total Cost of Ownership (TCO) burden due to the complexity of their legacy systems and processes. This makes them feel like there is little to no room for innovation, as every change is just so hard and costly to implement.
To enable more innovation, banks need to solve this dilemma and find a way to prioritise business opportunities and the productivity and efficiency of their operations while keeping on top of regulation. The question is how?
The first step is to consider how you could reduce the cost of running your end-to-end payments processing operation. It seems contradictory, but regulatory change programmes are excellent carrier projects for this kind of exercise, as they often impact the whole payments chain and attract a lot of senior management focus.
Banks, therefore, need to see these programmes as the vehicles that will enable them to rationalise, simplify and optimise their architecture and business processes. And with a never-ending cycle of regulatory change, this drives a constant cycle of improvement aligned with the Japanese concept of “Kaizen”. Simplification and rationalisation shouldn’t be a one-off exercise, it should be part of your cultural mindset.
The global ISO20022 migration is an excellent example of a change programme that will enable banks to rationalise, simplify and optimise. Banks with an innovative migration strategy will use this programme to:
Banks taking this approach will soon start to realise the benefits: running their payments business will be easier, less costly and more agile. With reduced complexity, their regulatory payments change programmes will be less invasive with a reduced impact to the organisation and customers, freeing up time and resources to deliver those strategic business outcomes and actions that enable the bank to compete for the future.
As the American author Peter Drucker said:
“Efficiency is doing things right. Effectiveness is doing the right things.”
Get it right, and you can deliver more change with less resources, allowing Innovation to once again sit at the top of your agenda, delivering solutions that add value for your customers and business.
Finally, innovation is a state of mind. To be effective, we must not only get better at optimising how we use our limited resources, but also nurture the right culture and growth mindset in our people!
Share this post
RedCompass Labs
Resource
ISO 20022 Migration: 5 must-haves for success
Wondering how banks can ensure a timely and successful migration? Download the "ISO 20022 Migration: 5 must-haves for success" white paper.
Download now
Migration was only ever the first invoice
Postponing by two weeks gives T2’s address rules a grace period, not a rewrite
Not so long ago digital money was written off as a niche experiment, irrelevant to mainstream…
Gated content
SR 2026 has been postponed until 2027
MT 101 is ending. Here’s what to do before the switch to pain.001
The clock is ticking...
Gated content
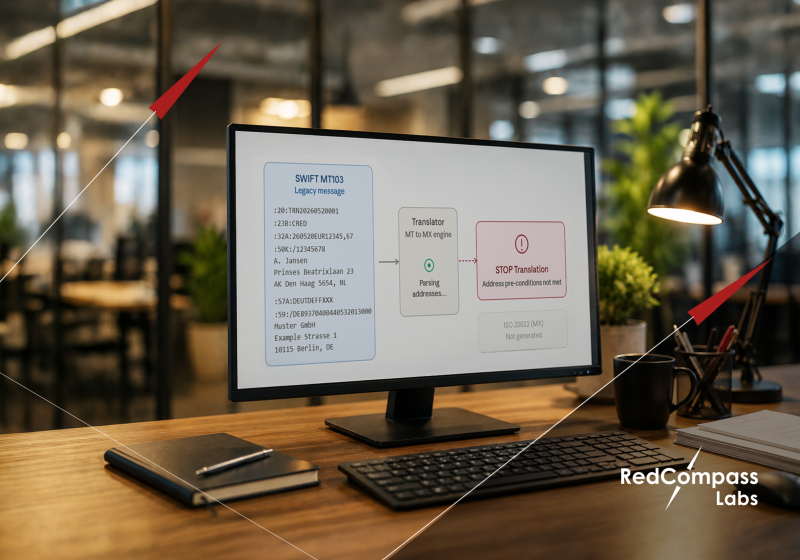
Banks face two major ISO 20022 deadlines in 2026. Will they meet them?
Most payments modernization projects overrun, go over budget, and fail to deliver to the original spec.