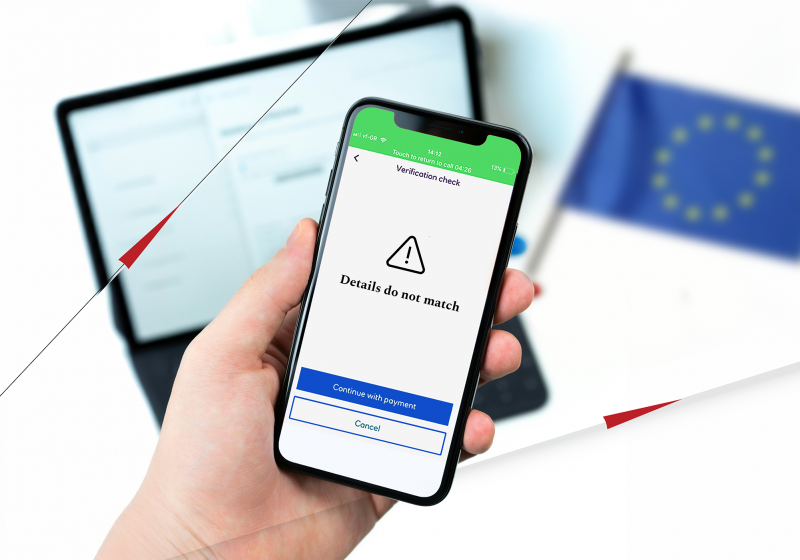
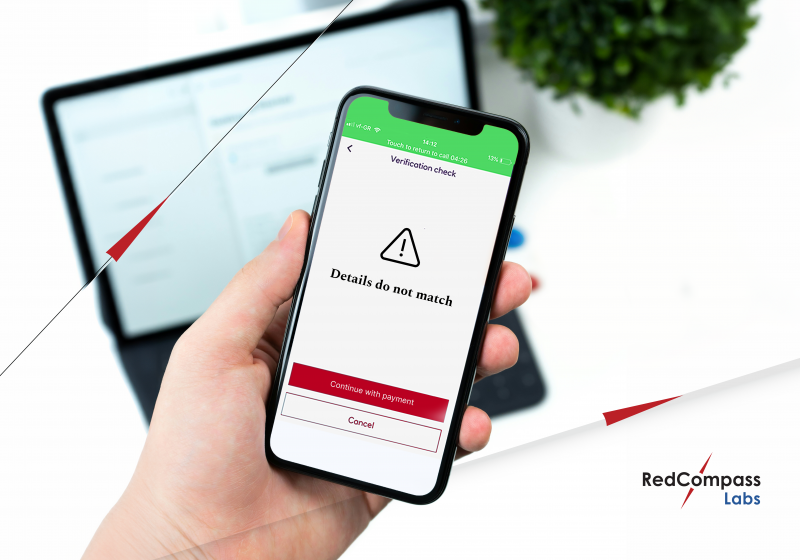
The other day I almost killed my husband! After many hours slaving over our 2020 summer vacations accounting (yes, it was May 2021!), I finally finished this (endless) boring exercise by sending him the equivalent of a request-to-pay through a Neobank app. What did he do? He let the request expire! Bringing us almost back to square one!
Of course, we should have been using our joint account card in the first place. But the reality is, we use our personal cards a lot to pay for purchases meant for the household, particularly when the joint account card is embarrassingly declined due to lack of funds. This got me thinking about banking products for couples. Or should I say, for partnership, marriages, or whatever! Bank products to keep us together!
To be fair, doing our accounting has gotten a bit easier thanks to providers like Flux since their introduction of digital receipts. For example, in the past, my hubby would charge me for his barber shave without telling me. He would believe that the UFO records that appeared on the statement must be either a scam or a household expense and would charge me for these receipts when in fact, half of them are for him!
Thinking about the future of payments, this exercise may go to a new level in terms of difficulty. Indeed, right now, we only have a couple of active cards. However, in the future, when there will be a multiplication of the payment rails as predicted by PwC*, the squaring up will be much more complicated. Not only would we need to check our bank statements thoroughly, but also tokens/NFTs balances and spending on closed loops like super apps or digital wallets. Just the thought of doing this forced me to find an alternative solution.
Can we leverage Open Banking?
At first, I thought about Splitwise or Curve and their ‘go back in time functions’ because – I quote – “accidents happen”. But I saw two problems:
- you can only go back up to 90 days, which is not enough to correct summer entries (when you review them in the following May), and
- when I go abroad and use a Neobank.
It is not an accident; I use a Neobank on purpose as I do not wish to be robbed by my incumbent bank with a ridiculous FX rate and extortionate fees! So, I dropped this idea.
Then, I remembered about Open Banking and the consultation launched at the beginning of the year on the potential implementation of variable recurring payments and sweeping**, without the need for authentication for each individual payment. For sure, the focus has been mainly on automatic transfer to saving accounts where the amount is established by an AI, like Plum, Snoop or Cleo offer. However, money management was included in the consultation***. Imagine, an automatic funding request could be automatically sent to our personal account with the required amount without the card being declined, with, of course, a daily limit like the one implemented by NatWest recently to improve fraud protection.
In our Future of Payments workshop, RedCompass Labs is often asked about potential use cases for Open Banking. Well, here is one: providing real added value for customers and making the full payments experience more seamless! Half of the population in Northern Europe is either married or in a civil partnership. All other regions of the globe have even higher rates. Let alone the couples working on the basis that ‘what is mine is yours’, that should leave a significant target market for banks, Neobanks or, to some extent, Personal Finance Management (PFM) tools which already offer a consolidated view.
Are Neobanks’ Minimum Viable Products (MVP) too narrow?
To be honest, I was very surprised that the Neobank I am banking with doesn’t offer the functionality described above, and in fact, it doesn’t even offer joint accounts. I was even more surprised to see that the request-to-pay I sent couldn’t be found anymore in the app, not even by their customer service. I fully appreciate that working in an agile framework and thinking about a minimum viable product is the new default operating model. However, are the MVPs becoming too narrow? Having all the operations related to your account seems like a basic functionality to me.
Using data analytics applied to payments, banks could slice and dice the data to identify the minimum functionalities required to address the real pain points of a focussed customer segment, and therefore, differentiate themselves. This is actually the way to maintain revenue in banking, according to McKinsey.
The success of some banks like Chetwood, who have already embarked on this journey and use data to create targeted products, demonstrates that using data is probably the way forward. And I am very glad to see that our team at RedCompass Labs is already going in this direction and leveraging data to increase operational efficiency. Who knows? Our D1R4Payments might be the missing secret to save a lot of marriages!
Disclaimer:
– If I have missed the magic bullet and you know how to solve our issue, please feel free to comment!
– Since then, we also decided to try a Monzo joint account, just to see 😉
* See Trend 2, 3, 4
** The Competition and Markets Authority (CMA) refers to this mechanism for automated funds movement as “sweeping” within its Retail Banking Market Investigation Report
*** See page 6